Manufacturing in China for Export: Processing Trade, Duty Drawback and Re-Export Compliance
Foreign manufacturers producing in China for export can cut duties through processing trade and duty drawback — but the customs supervision is strict. How the bonded manuals work, what triggers a customs audit, and how to stay compliant.
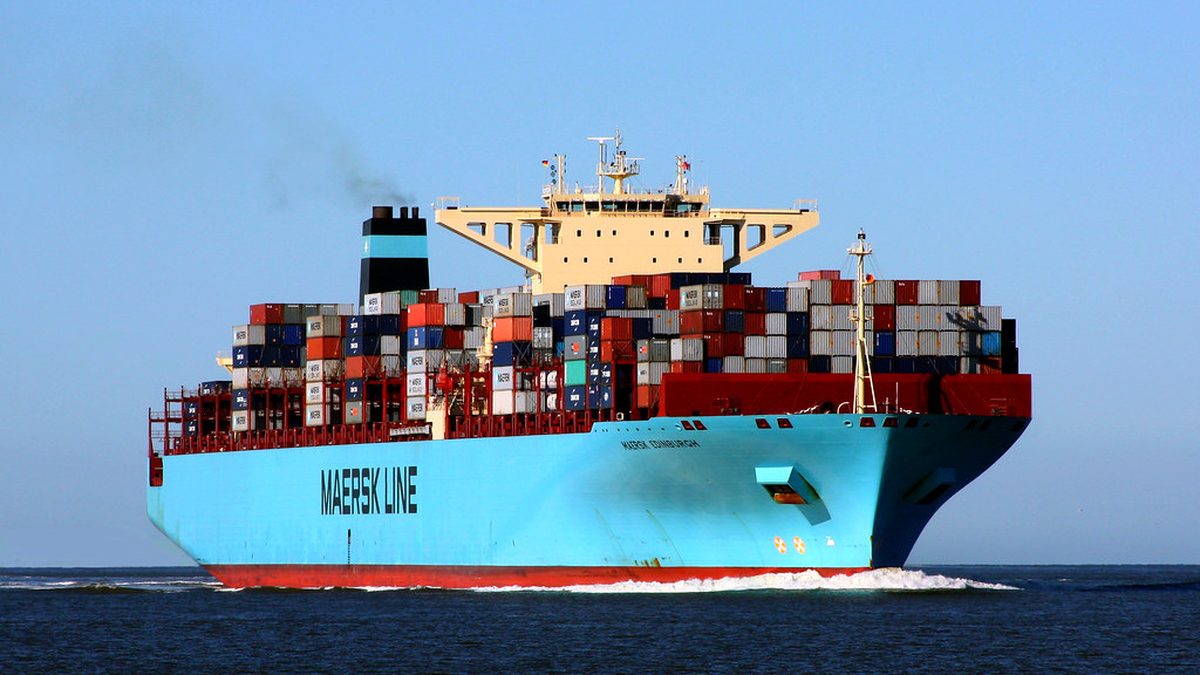
A factory in China making goods for export sits inside two overlapping regimes: customs supervision over the materials it brings in, and the tax system's refund of the VAT embedded in what it ships out. Done correctly, the two regimes take a large chunk of cost out of the product. Done carelessly, they convert savings into a customs penalty and a denied refund. This guide explains how the machinery works and where it fails.
Two ways to make goods in China for export
There are two basic structures. Under processing trade (加工贸易), imported materials are exempted or bonded from import duty and import VAT on the condition that the finished goods are exported; the materials never formally "enter" China's domestic market. Under general trade (一般贸易), the factory imports materials and pays duty and VAT up front, then claims a refund of the input VAT when the finished goods are exported. Processing trade saves the up-front cash; general trade is simpler but ties up working capital.
Processing trade: the two flavors
- Processing with supplied materials (来料加工): the foreign party supplies the materials, the Chinese factory processes them for a fee, and the goods are re-exported. The factory generally does not own the materials.
- Processing with imported materials (进料加工): the factory imports the materials itself, processes them, and exports the finished goods. This is the more common structure for a foreign-invested manufacturer.
Both flavors are regulated, not just registered. The imported materials remain under customs supervision from entry until the finished goods are exported and the relevant procedures are closed out.
The bonded manual and what it binds
Processing trade is administered through an electronic handbook (加工贸易手册) that records the quantities of materials to be imported and the quantities of finished goods to be exported, and links them through a consumption ratio. Customs compares what you imported, what you exported and what is left. The three things that get an enterprise in trouble are a mismatch between the declared consumption ratio and reality, materials that "disappear" into the domestic market without being taxed, and leftover materials or scrap that are never properly disposed of. Every unit of material must end up in an export, in a taxed domestic sale, in an approved write-off, or in the approved handling of the surplus.
Duty drawback and the export VAT rebate
The export VAT rebate (出口退税) is the second lever. China refunds input VAT on exported goods, but not always at the full rate: the refund rate depends on the product, and the government adjusts rates from time to time, sometimes cutting or removing the rebate for specific categories it wants to discourage from exporting. The refund is calculated through the "exempt, credit, refund" (免抵退) method for production enterprises, which nets input VAT against the output that would have been due on domestic sales. The practical points are to confirm the current refund rate for your HS code before you price the product, and to keep the VAT invoices and the export documentation aligned, because the refund is claimed on the strength of that paper.
Where the compliance failures happen
- Declaring a consumption ratio that does not match the actual bill of materials, so the handbook can never balance.
- Selling leftover materials, scrap or finished goods domestically without paying the duty and VAT that becomes due.
- Using materials imported under one handbook for a different production line or a different customer.
- Claiming an export VAT rebate without the matching purchase invoices, customs declarations and payment records.
- Letting the handbook lapse without closing it out, which leaves the enterprise open to a customs audit and penalties.
Customs audits and what they check
China customs audits post-clearance, and processing-trade and export-rebate enterprises are a priority. The audit reconstructs the flow — import declarations, handbook entries, production records, export declarations and the VAT refund claims — and looks for the gaps between them. The records that matter are the ones most factories keep loosely: the actual bill of materials, the production and inventory logs, and the evidence of how leftover materials were handled. For the audit framework, see China Customs Audit and Post-Clearance Compliance: A Guide for Importers.
Practical checklist
- Choose the structure deliberately — processing trade or general trade — based on cash flow, not habit.
- Register the handbook with a consumption ratio that matches your real bill of materials.
- Track every unit of imported material to its end: export, taxed domestic sale, or approved disposal.
- Confirm the current export VAT refund rate for your HS code before pricing.
- Keep the invoice, declaration and payment trail aligned for every refund claim.
- Close out handbooks on time and keep the production records an auditor will ask for.
Processing-trade rules, the electronic handbook system and export VAT refund rates are adjusted by Chinese customs and tax authorities from time to time, so confirm the current rules for your product and your location before committing to a structure. This content is general information and does not constitute legal or tax advice.
The savings in processing trade and duty drawback are real, but they are conditional savings — conditional on the goods actually being exported, the materials actually being traceable, and the paper actually matching the physical flow. The manufacturer who treats the handbook and the refund as a discipline keeps the margin; the one who treats them as a formality gives it back, with a penalty on top.
Related articles
China Labor Unions and Collective Consultation: A Guide for Foreign Employers
China's labor-relations framework adds a union and consultation layer that foreign employers often overlook. How unions work, what a collective contract binds, the 30-day rule for layoffs, and the consultation steps you must document.
China Annual Corporate Income Tax Filing for WFOEs (汇算清缴)
A WFOE pays corporate income tax provisionally all year, then settles the real number in the annual 汇算清缴 filing due by 31 May. How the process works, the adjustments foreign companies miss, and the penalties for late or wrong filing.
China ICP and Value-Added Telecom Licenses: How Foreign Companies Launch Websites and Apps Legally
An ICP filing and an ICP licence are different things, and a foreign-owned site or app may also need a value-added telecom licence such as an EDI licence. What each covers, the foreign-ownership rules, and how to apply.